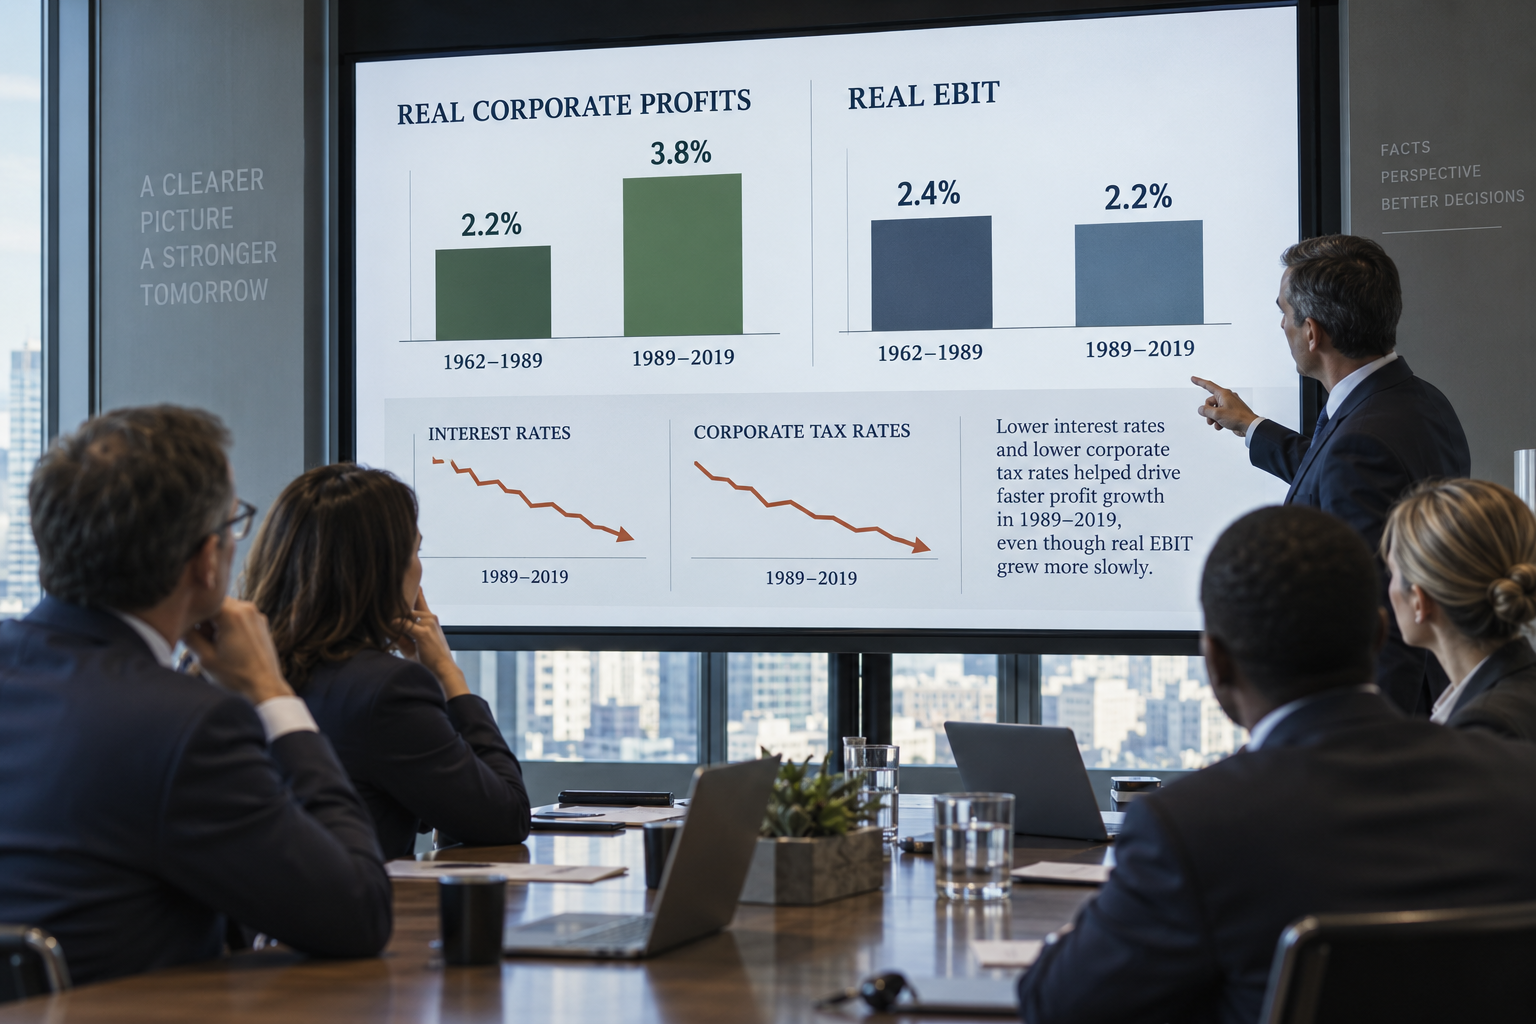
The thirty-year stretch before the pandemic stands out as exceptional. Real corporate profits grew at 3.8% per year from 1989 to 2019, nearly double the 2.2% pace seen from 1962 to 1989. But here’s what makes this period remarkable: the difference in profit growth was due to declining interest and corporate tax rates. Real EBIT growth was lower in the later period at 2.2% versus 2.4% per year. Businesses weren’t operating better; they were paying less to debtholders and tax authorities.
Why High Growth Is Dead: The Shift to Profitability and Growth That Actually Lasts
Published by grace • September 7, 2026
The era of extraordinary profitability and growth is coming to an end. Corporate net income grew at an impressive 7% per year from 1989 to 2019, nearly triple the 2.5% rate of U.S. real GDP growth. Operational brilliance alone didn’t drive this remarkable expansion. Declining interest rates and corporate tax cuts were responsible for over 40% of real profit growth during this period. But those tailwinds have disappeared, and we’re now facing a fundamental move in how businesses must approach growth.
Understanding the difference between growth and profitability has never been more critical. We’ll explore why the high-growth era is ending and how to balance business growth and profitability in this new environment with strategies that deliver revenue growth and profitability that lasts.

Declining interest rates fueled corporate profit expansion
The decline in risk-free rates alone explained the expansion in price-to-earnings multiples during this period. Lower interest expenses boosted corporate profits and reduced financing costs for publicly traded corporations by more than a third since the 1980s. We paid nowhere near as much for that capital at the time we borrowed money to grow. This created a direct lift to bottom lines without requiring any operational improvements.
Lower corporate tax rates boosted bottom lines
Corporate tax rates dropped over these three decades. The effective corporate tax rate for S&P 500 nonfinancial firms declined from 34% in 1989 to 15% in 2019. The Tax Cuts and Jobs Act of 2017 accelerated this trend and cut the statutory corporate tax rate from 35% to 21%. Effective corporate tax rates fell from 23% in 2016 to 15% in 2019 following this reform. A declining share of corporate earnings flowed to tax authorities and left more for stockholders.
Technology and scale advantages amplified returns
The digital world amplified advantages of scale for large, tech-driven firms. Scale enables companies to spread fixed costs over greater output and reduce per-unit costs. This allows either lower prices or higher margins. Access to capital represents an enormous advantage, especially when you have technology companies that require large amounts of money to find and deploy new technologies. Big data provided another competitive edge, as large companies had an advantage in collecting proprietary data.
Asset-light business models improved margin growth
The changing composition of the S&P 500 adjusted profitability dynamics. Asset-light companies outperformed their asset-heavy peers by four percentage points in total shareholder returns over five years. Traditional hotel chains owning properties achieved roughly 8-12% ROIC, while hotel platforms owning software ran roughly 20-40%. Asset-light models delivered better returns on assets and greater flexibility than asset-heavy models.
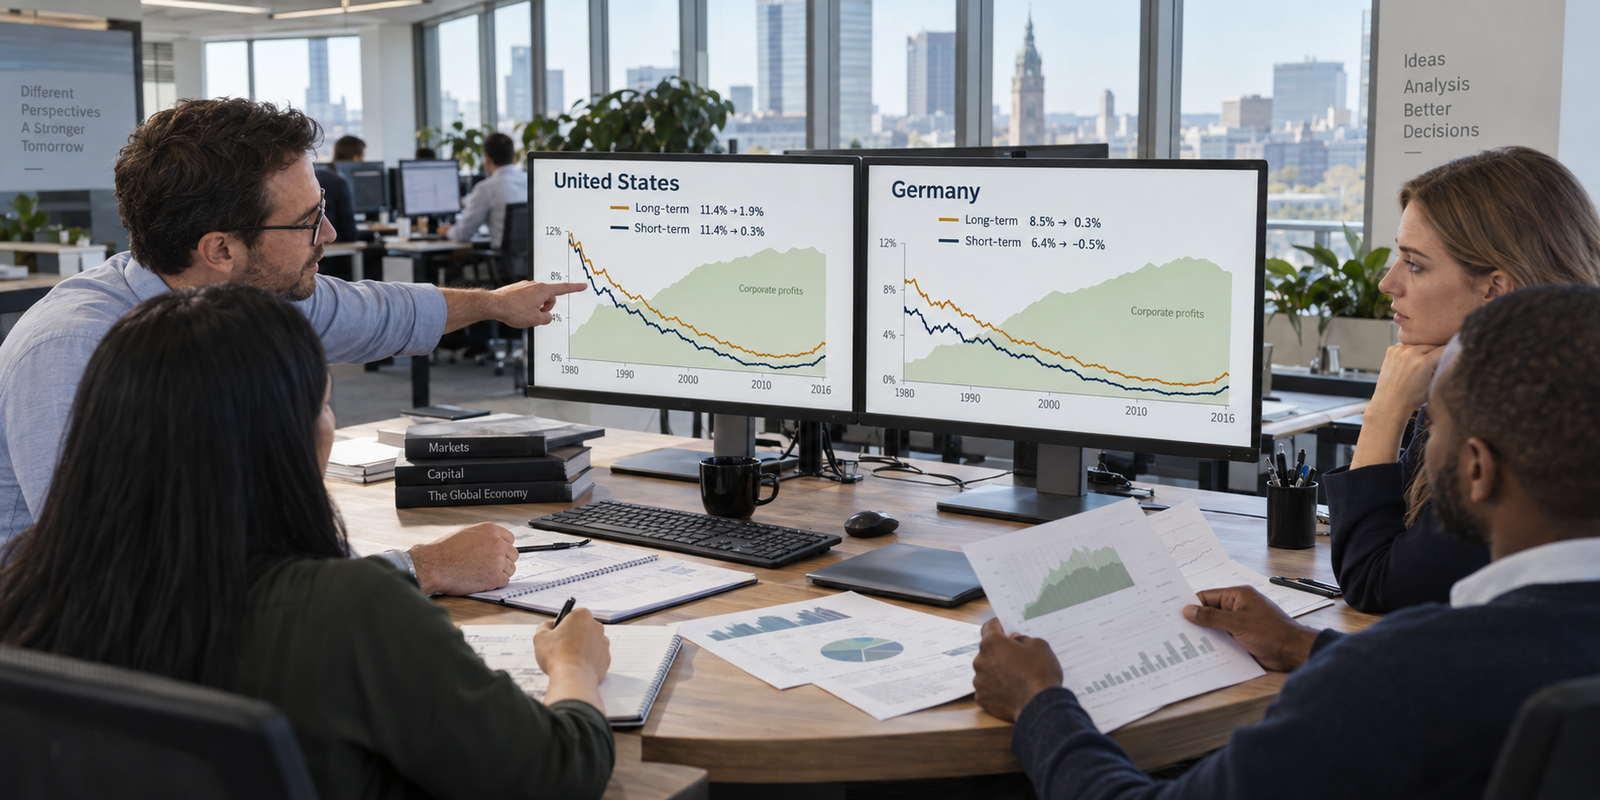
The structural advantages that powered three decades of exceptional profitability are reversing. Interest rates dropped from 11.4% in 1980 to just 1.9% by 2016 across the United States. Germany saw an even more dramatic fall, from 8.5% to 0.3% over the same period. Short-term rates followed the same trajectory and declined from 11.4% to 0.3% across the United States and from 6.4% to negative 0.5% across Germany. These declines created an unprecedented tailwind for corporate profits that can’t be repeated.

Interest rates have hit their floor
We’ve reached what economists call the zero lower bound, the natural limit to how low interest rates can go. Cash under a mattress becomes more attractive when deposit rates hit zero because lowering them further means depositors must pay to hold money. Central banks struggled with this constraint during the Great Recession and were forced to resort to unconventional tools like quantitative easing. Financial markets now price just a 4% probability of hitting the zero lower bound within two years. So the era of ever-declining borrowing costs has ended.
Corporate tax rates can’t fall much further
The U.S. federal corporate tax rate stands at 21% and is arranged with the OECD average that has remained at 21% since 2019. Combined with average state rates of 4.8%, our total effective rate reaches 25.8%. Corporate tax revenue as a share of GDP is higher now than before tax reform, despite reduced statutory rates. There’s limited room for further cuts without sacrificing revenue stability.
The cost of aggressive growth is rising
Aggressive growth strategies experience drawdowns of 10.8% or higher, compared to moderate strategies seeing median drawdowns around 5.08%. These strategies involve high turnover and chase stocks with short-term performance. They come with higher management fees that reduce net returns.
Market concentration and regulatory pressures
A handful of tech companies now control communication channels and gatekeep economic opportunities. Major antitrust suits target Big Tech, with the European Commission issuing a $5 billion fine to Google for unfair practices. Biden administration merger guidelines lowered concentration thresholds from an HHI of 2,500 to 1,800. Regulatory scrutiny makes aggressive expansion through acquisitions more difficult.
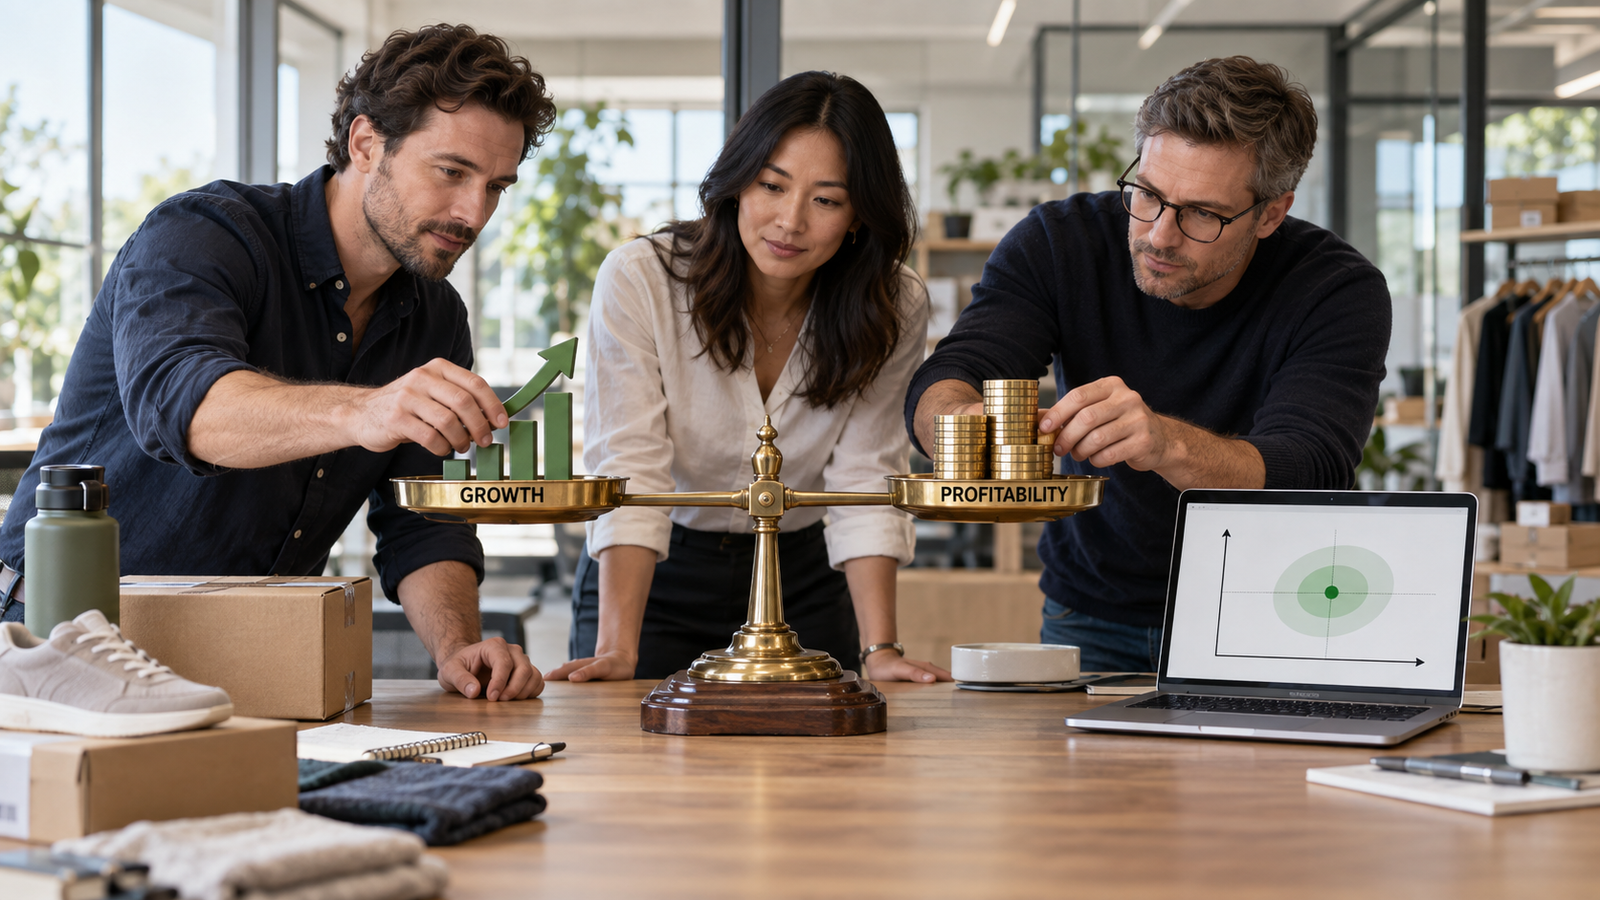
Growth and profitability balance has become the defining challenge. Neither metric alone tells the full story of business health. Understanding how they interact determines survival.

Understanding the difference between growth and profitability
Growth represents expansion in operations, employees, market share, or product development. Profitability refers to keeping gross earnings above expenses. Revenue shows demand for products or services. Profit reveals what remains after all costs are paid. Both are vital for long-term success, but they serve different purposes.
Revenue growth and profitability as complementary goals
Profitability stimulates business growth and profitability. Profit provides resources for expansion. Growth creates opportunities for greater profits. A focus on revenue growth without corresponding profitability results in financial instability, as rising costs may outpace income. Prioritizing profit without revenue growth creates stagnation and inability to compete.
The Rule of 40 and sustainable business metrics
The Rule of 40 states that a SaaS company’s revenue growth rate plus profit margin should equal or exceed 40%. Companies exceeding this threshold achieve premium valuations. Top-quartile SaaS companies generate nearly three times the multiples of bottom performers.
Cash flow matters more than vanity metrics
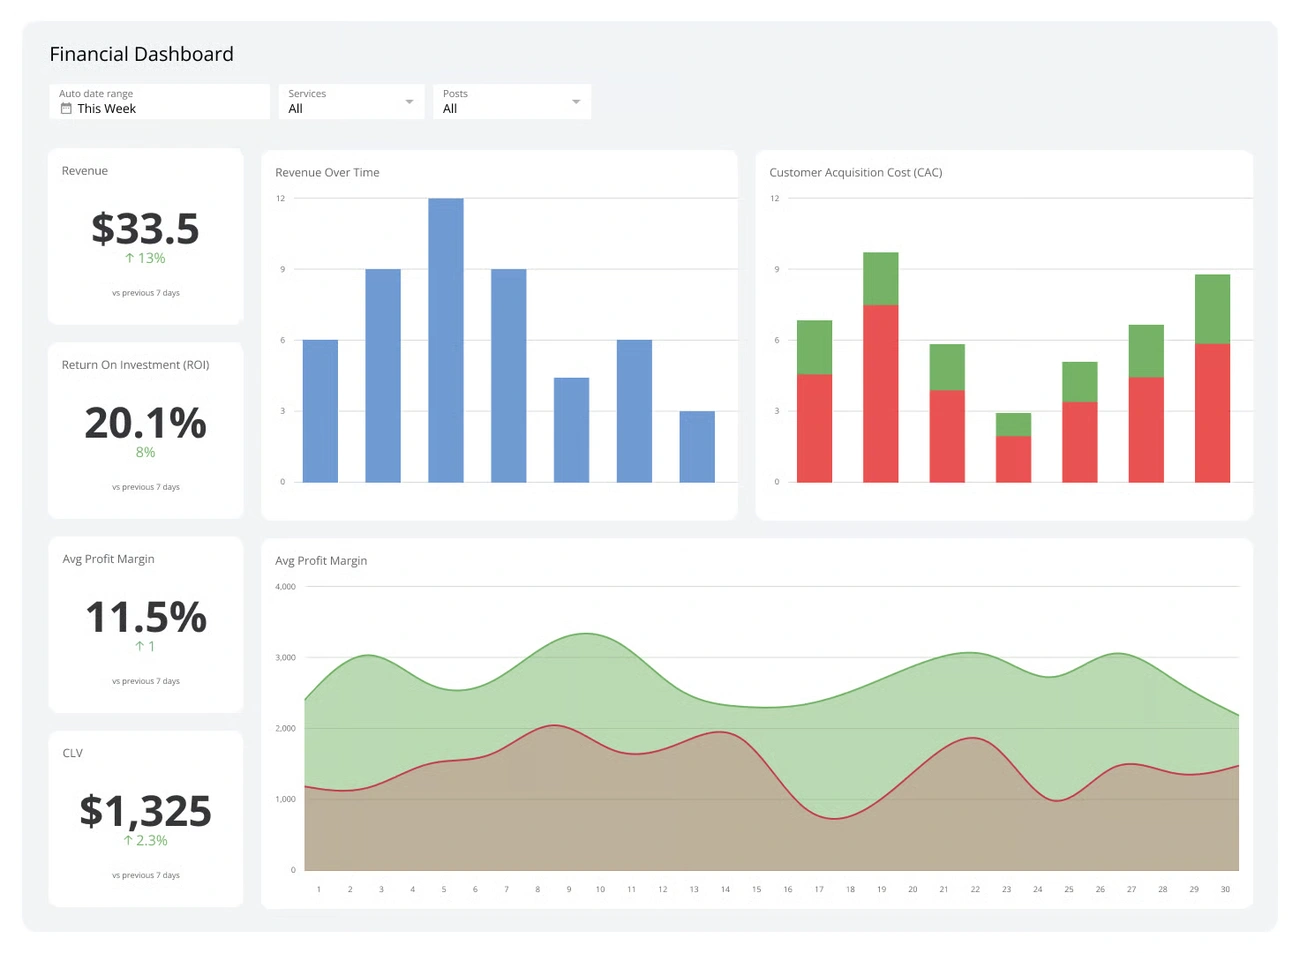
Cash flow determines whether you can pay bills, not accounting profit. Profitable companies lacking cash and unable to borrow face bankruptcy. Revenue obsession creates dangerous blind spots. Top-line numbers represent the biggest, most impressive figure without revealing actual financial health.
Sustainable expansion requires fundamentally different tactics than the growth-at-all-costs playbook.

Focus on unit economics and customer acquisition efficiency
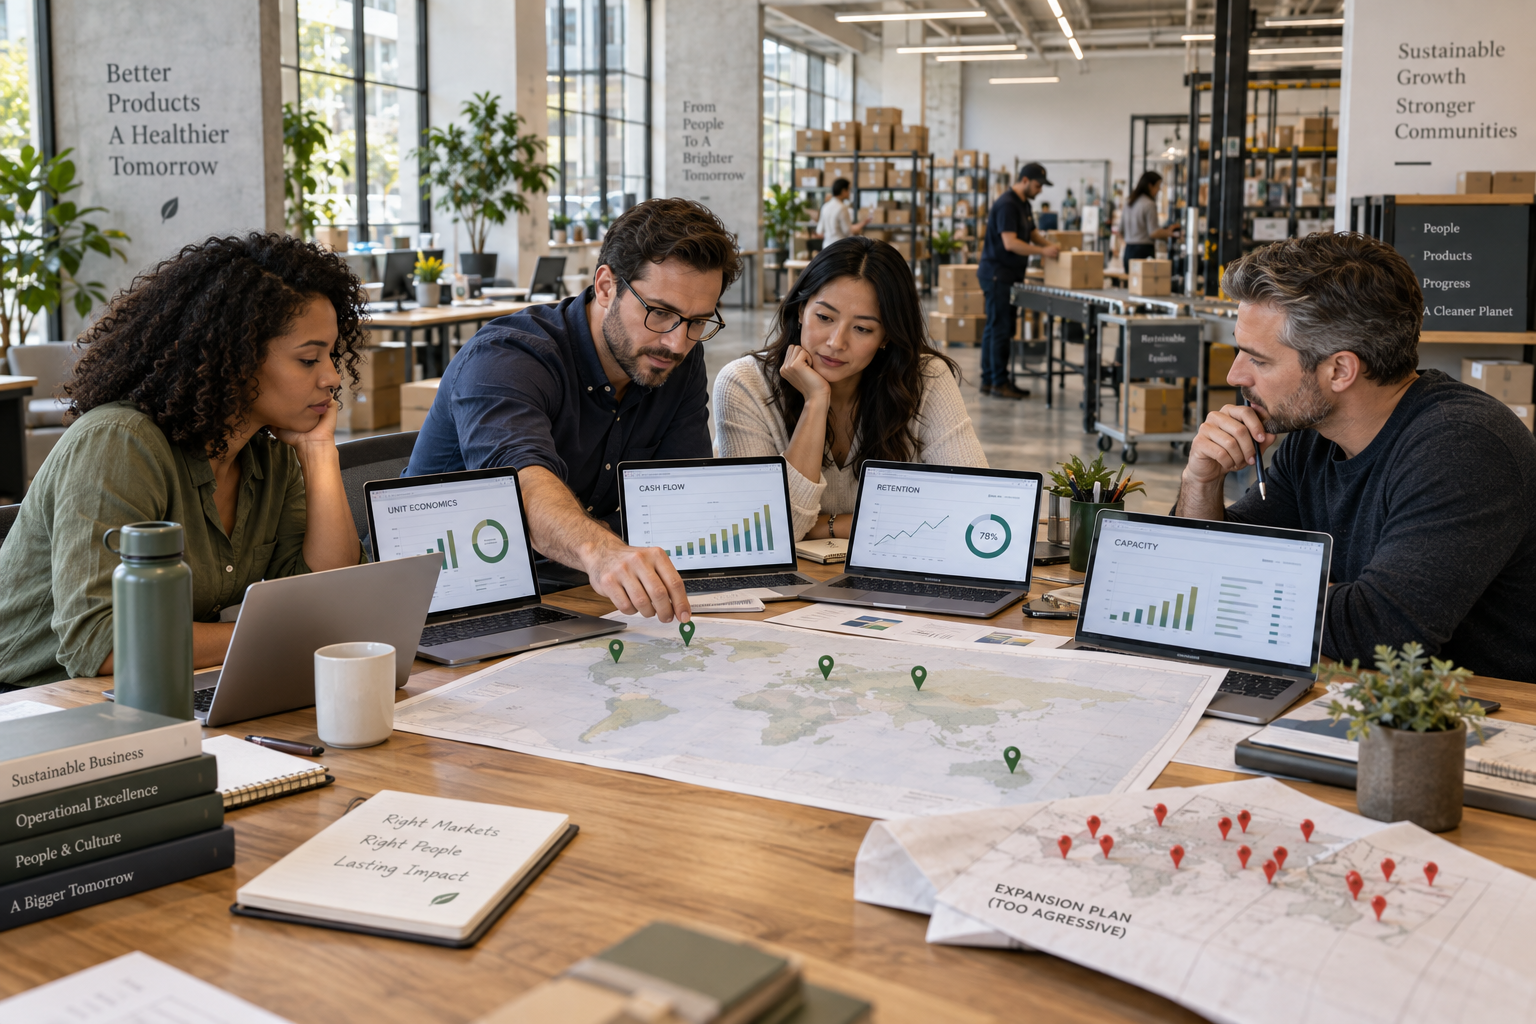
The LTV:CAC ratio tells us whether our business model works. A ratio of 3:1 serves as the widely cited standard: we earn three dollars back for every dollar spent acquiring a customer. Below that threshold, acquisition costs run too high or retention proves too weak. Retention is the most efficient method to raise LTV, as a 5% increase in customer retention can boost profits by 25% to 95%.
Build scalable growth with profitable cohorts
Cohort retention analysis tracks users who start together and measures how many return in later periods. We can see patterns that individual models often blur when we group users by acquisition date or channel. Higher retention translates to higher lifetime value, while cohort analysis reveals which channels bring customers who return within 60 days versus those who never pay back.
Adapt your strategy to your cash position
Bootstrapping means building our company using personal savings, reinvested revenue, or small non-dilutive funding. It demands focus on profitability early and prioritizes long-term sustainability over hypergrowth. The approach offers full founder ownership and control. We may be better positioned to bootstrap successfully if we have clear product-market fit, low capital requirements, and strong margins.
Create optionality through efficient operations
Operational optionality is knowing how to change how we deliver an outcome without first rebuilding our operating model. It can include a second supplier that has already been qualified, spare production capacity, or cross-trained staff. Maintaining backup capabilities carries visible recurring costs. The alternative is less frequent but potentially much larger: lost sales, customer compensation, and reputational damage.
Chart a glide path from growth to profitability
A glide path is the plan that adjusts our mix of investments as we approach our goal. Younger companies can afford to take more risks with higher growth allocation, which captures expansion but is diversified with just enough conservative positioning to temper the worst downturns. We start to reduce growth exposure to build a more conservative portfolio in preparation for sustained profitability.
The high-growth playbook powered by declining rates and tax cuts has run its course. We must rebuild our growth strategies around fundamentals that matter: unit economics and cash flow. External tailwinds can’t be relied upon anymore.
Focus on metrics that reveal true business health rather than vanity numbers. Build optionality through efficient operations and chart a clear path from expansion to profitability. That’s how we create growth that lasts.